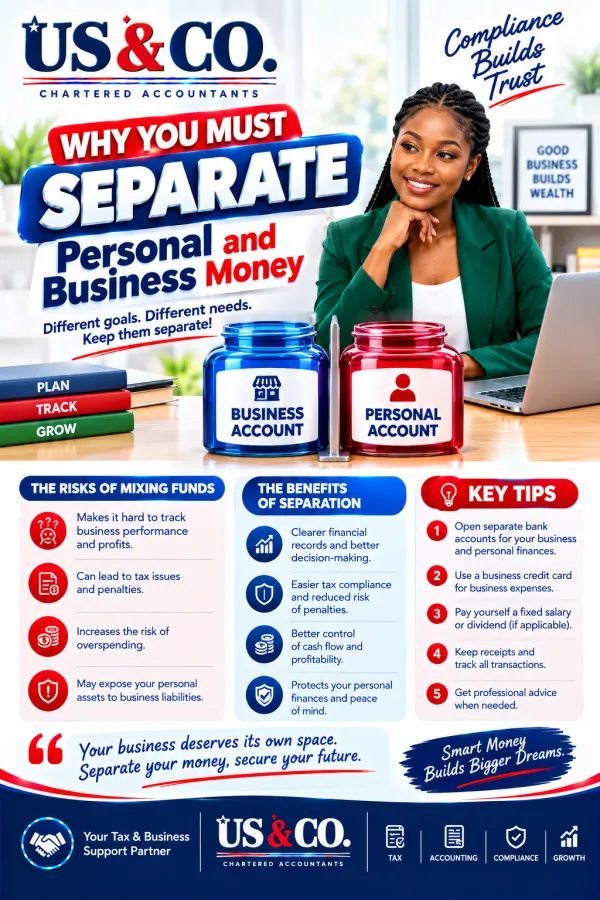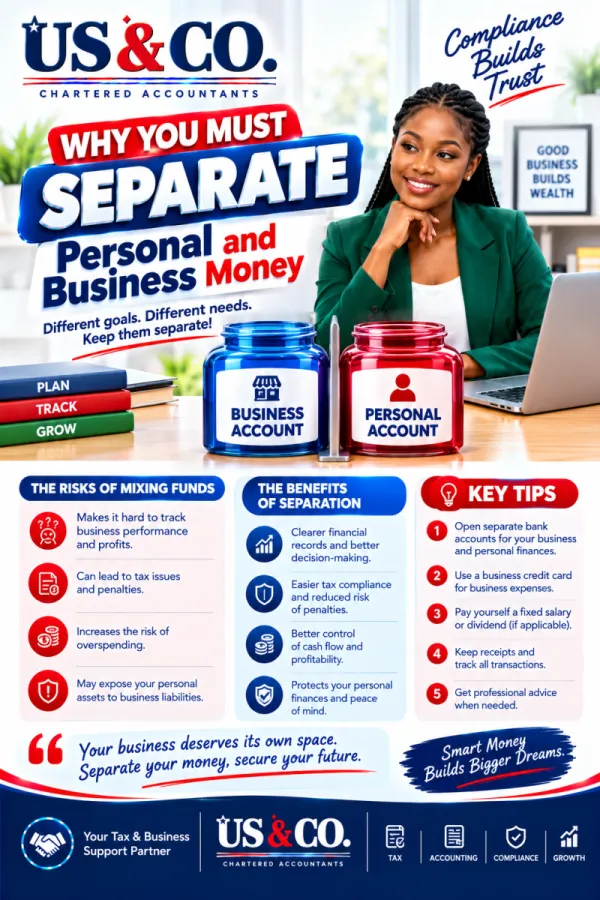
One of the most common, and most costly, habits among small business owners in Nigeria are running business income and expenses through a personal bank account, or using a single account for both. It feels simpler in the short term. In practice, it creates tax exposure, obscures the true performance of the business, and can undermine the legal protection a registered company is supposed to provide.
How it works
Separating personal and business money means maintaining a dedicated business bank account, used exclusively for business income and expenses, with the owner drawing a defined salary or distribution from the business rather than spending directly from business funds for personal needs. For a registered company, this separation is not simply good practice; it is part of what maintains the legal distinction between the company and its owners.
Why this matters to taxpayers
- Mixed accounts make it extremely difficult to determine actual business income and expenses, which directly affects the accuracy of tax computations.
- Where a tax authority reviews a business with mixed finances, total deposits into the account, including personal funds, may be treated as business income unless clearly proven otherwise.
- For a limited liability company, consistently mixing personal and company funds can, in some circumstances, undermine the separation between the owner and the company, a concept sometimes referred to as the corporate veil, with legal as well as tax consequences.
- Lenders, investors and auditors view mixed finances as a sign of weak financial control, which can affect a business's ability to raise financing.
Tax implications
- Business expense deductions become harder to support when personal and business spending are mixed in the same records, increasing the risk of disallowance.
- Personal withdrawals from a company's funds, where not properly structured as salary, dividends or a documented loan, may raise questions about their tax treatment.
- A tax audit of a mixed account may treat ambiguous inflows as taxable business income, since the burden generally falls on the business to prove otherwise.
- VAT and withholding tax tracking becomes significantly harder when business transactions are not isolated from personal ones.
Step by step: separating your finances properly
- Open a dedicated business bank account in the business's registered name.
- Route all business income into that account, with no personal deposits mixed in.
- Pay all business expenses from that account, rather than paying with personal funds and reimbursing later without documentation.
- Decide how you will draw funds for personal use, whether as a formal salary, a documented dividend, or a properly recorded director's loan.
- Keep a clear, written record of any transfer between personal and business accounts, with a stated purpose.
- Reconcile both accounts separately and regularly, rather than treating them as one combined pool of money.
- Review your structure periodically as the business grows, since what worked at a very small scale may need to formalize further.
Why engage a professional consulting firm
- Structuring how an owner draws funds from the business in a tax-efficient and properly documented way.
- Reviewing historical mixed transactions to help untangle and correctly classify them before a filing deadline or audit.
- Advising on the practical and legal implications of mixed finances for a specific business structure, whether sole proprietorship, partnership or limited company.
- Setting up bookkeeping systems that make separation easy to maintain going forward.
Why every business should comply
Separating personal and business finances protects the business owner as much as it protects the tax authority's ability to assess tax accurately. It makes a business's performance visible, supports every tax filing with clean records, and preserves the legal protections that come with proper corporate structure.
Tips and points to watch
- Avoid paying personal bills directly from a business account, even temporarily, without clear documentation and repayment.
- If you must use personal funds for a business expense, record it as a loan to the business and repay it formally.
- Review your account statements monthly specifically to check that no personal spending has crept into the business account.
- Treat your own compensation as a planned, recorded transaction, not an ad hoc withdrawal whenever cash is needed.
Relevant law
- Nigeria Tax Act, 2025 and Nigeria Tax Administration Act, 2025 (basis for income assessment and record-keeping)
- Companies and Allied Matters Act (separate legal personality of registered companies)
Frequently asked questions
Is it illegal to use one account for both personal and business money?
It is not automatically illegal, but it creates significant tax, record-keeping and, for companies, potential legal risk, and is strongly discouraged as a practice.
How should I pay myself from my business?
Through a structured method such as a formal salary, a documented dividend, or a properly recorded director's loan, rather than ad hoc withdrawals.
What if I already have mixed accounts? Can this be fixed?
Historical records can often be reviewed and reclassified with professional help, though it is simpler to separate finances going forward as early as possible.
Does this apply to sole proprietors too, not just registered companies?
Yes. Even without a separate legal entity, keeping dedicated business records makes tax computation and compliance significantly easier and more defensible.
Where you need further assistance: You may contact US & CO. (Chartered Accountant), a professional tax consulting firm in Lagos, Nigeria.
📞 WhatsApp: 08056219998
📧 Email: info@usc.com.ng
🌐 Website: https://www.usc.com.ng
Footnote: This article is for general information only. It is not complete investment, tax or legal advice. Readers should consult a qualified professional and confirm current requirements with the relevant tax authority before making any investment or tax decision.