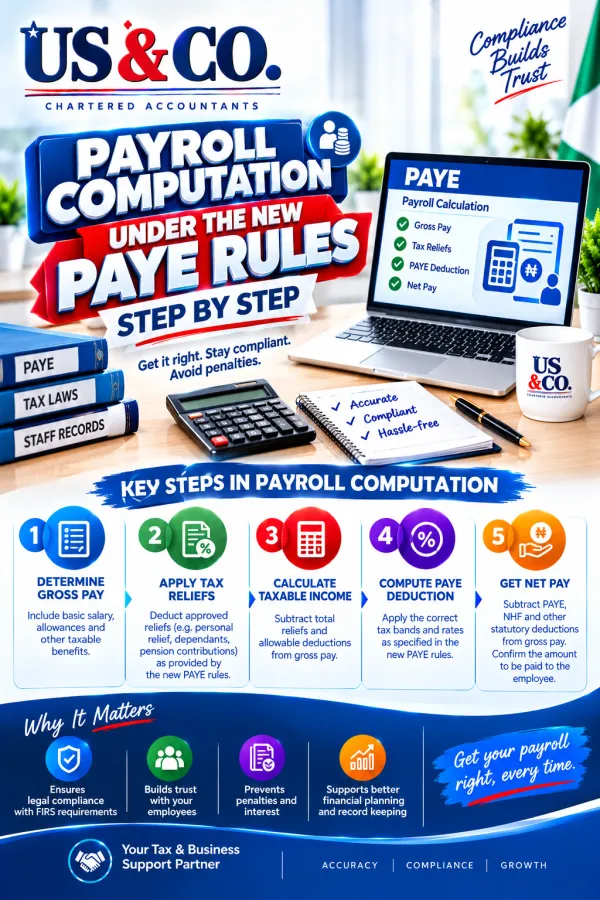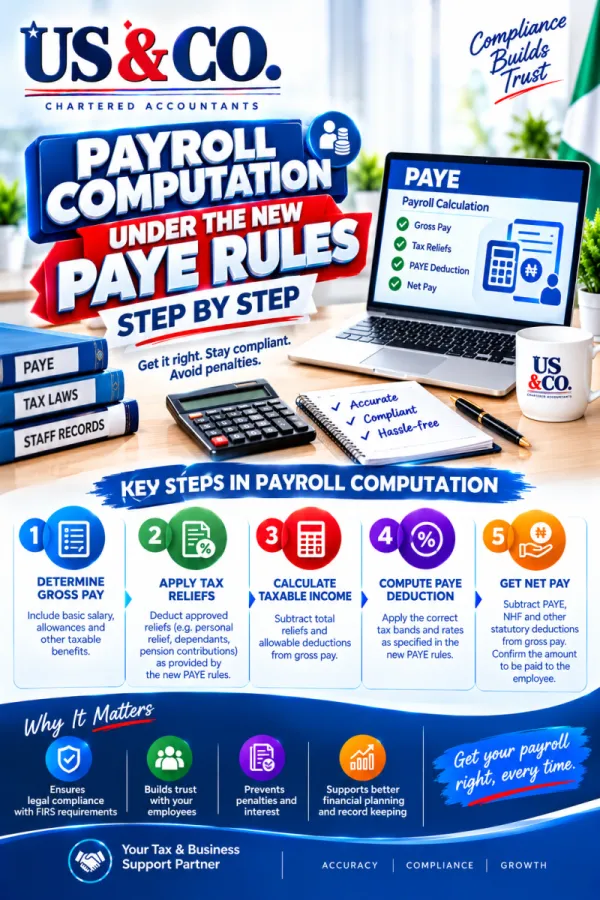
Running payroll correctly requires more than applying a tax rate to a salary figure. It involves identifying which components of pay are taxable, which deductions reduce chargeable income, and then applying the correct bands in the right order. This article walks through the computation in sequence, as it would typically be performed each pay period under the current rules.
How it works
Payroll computation under the Nigeria Tax Act, 2025 (NTA) generally follows this structure: start from gross emoluments, subtract statutory and other allowable deductions to arrive at chargeable income, then apply the personal income tax bands to that chargeable income to determine PAYE due.
Step by step: the payroll computation sequence
1. Determine gross monthly emoluments. This includes basic salary, housing allowance, transport allowance, and any other regular cash allowances paid to the employee.
2. Identify the pensionable pay base. Pension contributions are typically calculated on basic salary, housing allowance and transport allowance combined (sometimes referred to as "BHT"), not on the full gross pay, unless the employer's scheme states otherwise.
3. Calculate employee pension contribution. Apply 8% to the pensionable pay base, as set out under the Pension Reform Act, 2014, which remains unchanged under the tax reform.
4. Calculate employer pension contribution. Apply 10% to the same pensionable pay base. This is an employer cost on top of the employee's gross pay, not a deduction from it.
5. Identify NHF contribution, where applicable. Published guidance for 2026 indicates that NHF contributions are now voluntary for private-sector employees, with the employee choosing to opt in. Where an employee has opted in, 2.5% of basic salary is deducted and remitted to the Federal Mortgage Bank of Nigeria. Confirm current status for your specific workforce.
6. Calculate rent relief, where the employee has declared rent paid. 20% of annual rent paid, capped at ₦500,000, divided appropriately across the payroll period.
7. Arrive at chargeable income. Gross emoluments, less employee pension contribution, less NHF (if applicable), less rent relief (if applicable), less any other recognized deductions.
8. Apply the personal income tax bands to the chargeable income, band by band (see our earlier article on the revised PAYE bands for the full table and worked examples).
9. Arrive at net pay. Gross emoluments, less employee pension contribution, less NHF (if applicable), less PAYE calculated in Step 8, equals the employee's take-home pay.
10. Record the employer-only costs separately. Employer pension contribution (10%), NSITF (1% of monthly payroll) and, where applicable, ITF (1% of annual payroll) are employer costs and do not reduce the employee's pay, but should be budgeted and recorded.
Worked example
Assume an employee with a gross monthly salary of ₦500,000, made up of ₦300,000 basic, ₦100,000 housing and ₦100,000 transport, no other allowances. Assume the employee pays ₦1,200,000 in annual rent and has not opted into NHF.
- Pensionable base: ₦300,000 + ₦100,000 + ₦100,000 = ₦500,000
- Employee pension (8%): ₦40,000/month
- Employer pension (10%): ₦50,000/month (employer cost, not deducted from pay)
- Annual rent relief: 20% × ₦1,200,000 = ₦240,000/year (₦20,000/month)
- Chargeable income: ₦500,000 − ₦40,000 − ₦20,000 = ₦440,000/month, or ₦5,280,000/year
- Applying the bands: first ₦800,000 at 0% = ₦0; next ₦3,000,000 × 15% = ₦330,000... wait, the remaining chargeable income above ₦800,000 is ₦4,480,000, which falls partly in the 15% band (₦2,200,000) and partly in the 18% band (₦2,280,000)
- ₦2,200,000 × 15% = ₦330,000
- ₦2,280,000 × 18% = ₦410,400
- Annual PAYE: ₦740,400, or about ₦61,700/month
- Net pay: ₦500,000 − ₦40,000 (pension) − ₦61,700 (PAYE) ≈ ₦398,300/month
This example is illustrative only; actual figures depend on your specific payroll structure and should be verified.
Why this matters to taxpayers
Payroll errors compound across every pay period and every employee. A single mistake in the deduction sequence, for example applying rent relief after rather than before tax bands, or calculating pension on the wrong base, can result in under or over-deducted PAYE for an entire year.
Tax implications
- Incorrect sequencing of deductions changes the final PAYE figure, even if the individual percentages are correct.
- Employer pension and NSITF contributions are real costs that should be budgeted for separately from gross salary, not confused with employee deductions.
- Errors discovered late may require corrections across multiple pay periods, with resulting adjustments to remittances already made.
Why engage a professional consulting firm
- Correct sequencing of statutory deductions and reliefs before tax bands are applied.
- Template and system design, so payroll is computed consistently every month rather than recalculated from scratch.
- Periodic review, to confirm that payroll remains aligned with current rates and rules as they change.
Why every business should comply
Accurate payroll protects both the business and its employees. For the business, it avoids PAYE underpayment penalties and ensures employer-side contributions like pension and NSITF are properly funded. For employees, it ensures their pay, pension savings and tax records are all correctly calculated.
Tips for accurate payroll
- Build a standard payroll template with the deduction sequence fixed, so it is applied consistently every month.
- Review the pensionable pay base against your own compensation structure, since not every allowance is included.
- Confirm NHF opt-in status individually, given the shift toward voluntary private-sector participation.
- Reconcile payroll totals against remittance confirmations each month.
Relevant law
- Nigeria Tax Act, 2025 (personal income tax bands and reliefs)
- Pension Reform Act, 2014 (pension contribution rates)
- Nigeria Tax Administration Act, 2025 (PAYE filing and remittance)
Frequently asked questions
What is pensionable pay? Typically, basic salary, housing allowance and transport allowance combined, though this should be confirmed against your specific pension scheme documentation.
Is NHF still compulsory? Published guidance for 2026 indicates it is now voluntary for private-sector employees. Confirm current status before adjusting your payroll process.
In what order should deductions be applied? Statutory deductions and reliefs (pension, rent relief, NHF where applicable) are generally applied before the personal income tax bands, to arrive at chargeable income first.
Does rent relief reduce take-home pay or just the tax calculation? Rent relief reduces chargeable income, which reduces the PAYE calculated, which in turn increases net take-home pay. It is not a separate cash payment.
Where you need further assistance: You may contact US & CO. (Chartered Accountant), a professional tax consulting firm in Lagos, Nigeria. 📞 WhatsApp: 08056219998 📧 Email: info@usc.com.ng 🌐 Website: https://www.usc.com.ng
Footnote: This article is for general information only. It is not complete investment, tax or legal advice. The worked example is illustrative; actual payroll computations depend on individual circumstances and should be verified. Readers should consult a qualified professional before making any investment or tax decision.