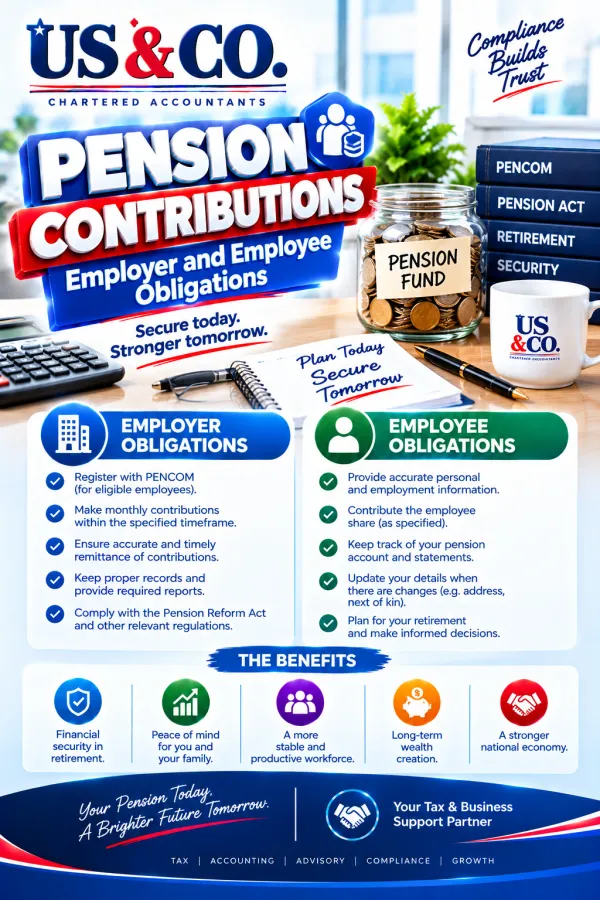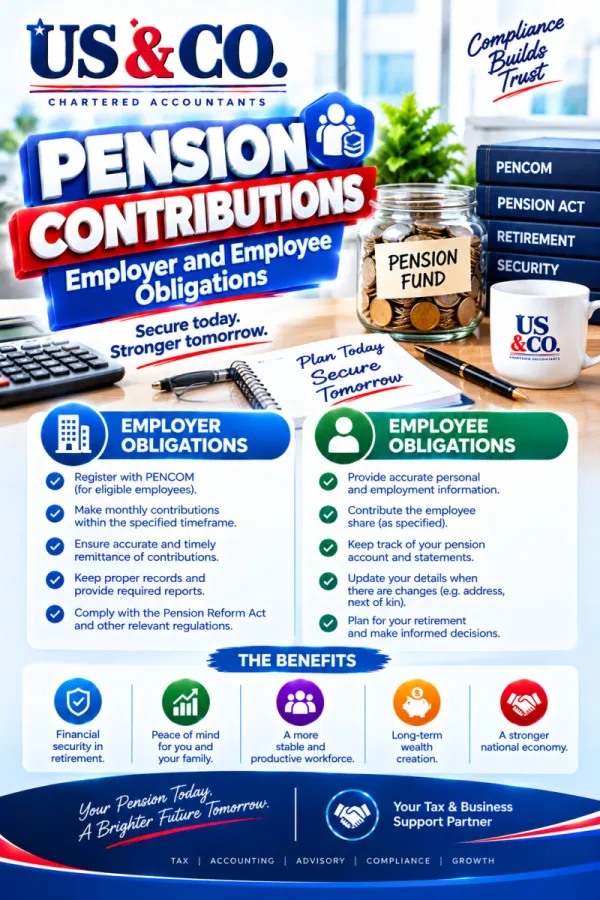
Nigeria's Contributory Pension Scheme has remained one of the most stable parts of the statutory compliance landscape, even as other tax rules have changed significantly under the 2025 reforms. This article sets out the current obligations for employers and employees under the Pension Reform Act, 2014.
How it works
Every employer with a qualifying number of staff is required to register with a licensed Pension Fund Administrator (PFA) on behalf of each employee, who holds a Retirement Savings Account (RSA). Contributions, calculated monthly, are remitted to a Pension Fund Custodian associated with the employee's PFA.
Contribution rates
The minimum statutory contribution under the Pension Reform Act, 2014 remains 18% of pensionable monthly emoluments, split as:
- Employee contribution: 8%
- Employer contribution: 10%
Pensionable emoluments are generally calculated as basic salary, housing allowance and transport allowance combined. The employer's 10% is an additional cost to the business, not a deduction from the employee's pay; both the employee's 8% and the employer's 10% belong to the employee and are credited to their RSA.
An employer may also elect to bear the full 18% (sometimes reported as a minimum of 20% under this option), with nothing deducted from the employee.
A note on the future rate: the National Pension Commission (PenCom) has proposed increasing the employer contribution rate as part of an ongoing review of the Pension Reform Act, disclosed at a 2026 pension consultative forum. As of this writing, published reports describe this as still at the consultation stage, not yet in force. Employers should not apply a higher rate until any amendment is formally enacted, and should monitor official PenCom communication for updates.
Why this matters to taxpayers
For employees, accurate and timely pension contributions directly affect retirement savings; a missed or late employer remittance is money that should have been earning returns in the employee's RSA. For employers, pension compliance is closely monitored, and a Pension Clearance Certificate is often required for government contracts and other regulatory processes.
Tax implications
- Employee pension contributions reduce chargeable income for PAYE purposes, so under-calculating them also affects the PAYE computation.
- Late remittance can attract penalties under PenCom's enforcement framework, in addition to any investment return the employee's RSA has missed out on.
- A common and costly error is deducting the employee's 8% from pay but failing to add the employer's 10% on top, which understates the amount that should reach the employee's RSA.
- Expatriate staff are generally covered under the same contribution obligations as Nigerian employees, based on published guidance.
Step by step: how employers should manage pension obligations
- Register the business with PENCOM, where not already registered.
- Ensure every eligible employee has an RSA with a PFA of their own choosing — employers cannot select this on the employee's behalf.
- Identify the pensionable pay base for each employee (typically basic, housing and transport).
- Calculate the employee's 8% and the employer's 10% each pay period.
- Remit both contributions together to each employee's Pension Fund Custodian, promptly after salary payment.
- Keep a per-employee remittance schedule showing the pensionable base, both contribution amounts, and proof of payment.
- File required returns with PenCom as applicable.
- Monitor for regulatory updates, including any change to the contribution rate following the ongoing PRA review.
Why engage a professional consulting firm
- Correct identification of the pensionable pay base, which can be inconsistently applied across different compensation structures.
- Avoiding the common error of remitting only the employee portion.
- Timely remittance tracking, to reduce exposure to penalties.
- Monitoring regulatory developments, such as the proposed rate change, so your business adjusts promptly once any amendment takes effect.
Why every business should comply
Pension compliance protects employees' long-term financial security and is a legal obligation for employers. Consistent compliance also supports a business's standing when a Pension Clearance Certificate is required, which is common for public sector contracts and certain regulatory approvals.
Tips and points to watch
- Confirm your employees' PFAs and RSA PINs are captured correctly during onboarding.
- Reconcile pension remittances against payroll each month, not only at year-end.
- Watch for news on the proposed PRA amendment, since organized labor and the private sector are both actively engaged in the ongoing discussion, and the eventual outcome will affect budgeting.
- Keep remittance evidence for the retention period required under PenCom's rules.
Relevant law
- Pension Reform Act, 2014
- Nigeria Tax Act, 2025 (deductibility of pension contributions in the PAYE computation)
Frequently asked questions
What is the current minimum pension contribution rate? 18% of pensionable monthly emoluments, split as 10% from the employer and 8% from the employee.
Has the rate increased recently? Not yet. An increase has been proposed by PenCom as part of an ongoing review, but published reports describe this as still at the consultation stage.
Can an employer choose the employee's PFA? No. Each employee selects their own Pension Fund Administrator.
Is the employer's 10% contribution deducted from the employee's salary? No. It is an additional cost borne by the employer, on top of the employee's gross pay.
Do expatriate employees need pension contributions? Published guidance indicates the same contribution obligations generally apply, though specific circumstances should be confirmed.
Where you need further assistance: You may contact US & CO. (Chartered Accountant), a professional tax consulting firm in Lagos, Nigeria. 📞 WhatsApp: 08056219998 📧 Email: info@usc.com.ng 🌐 Website: https://www.usc.com.ng
Footnote: This article is for general information only. It is not complete investment, tax or legal advice. Rates and requirements should be confirmed with PenCom directly, particularly given the ongoing review of the Pension Reform Act. Readers should consult a qualified professional before making any investment or tax decision.