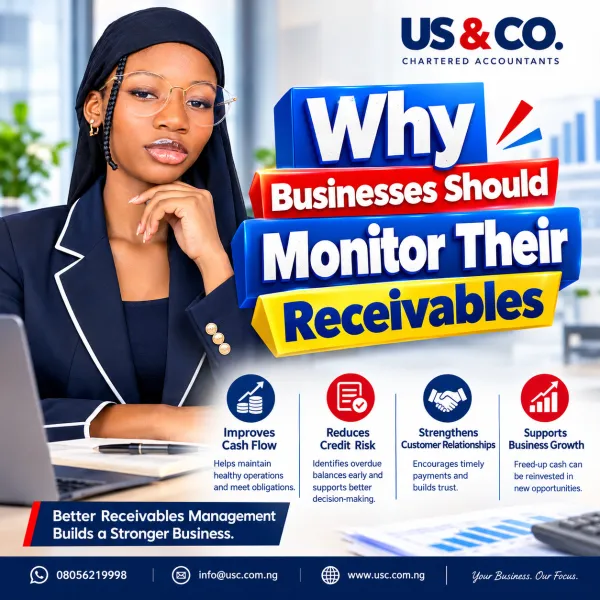
Why businesses should monitor their receivables
Why businesses should monitor their receivables” is a practical question for every management team that works with credit sales, agreed payment terms, and unsettled invoices. For taxpaying entities in nigeria, monitoring receivables is not only about cash flow; it also supports correct revenue reporting, proper tax computations, and defensible record-keeping during reviews, assessments, or audits.
In this context, us & co. (chartered accountant) approaches receivables management as part of sound governance: aligning internal controls with nigeria’s tax administration expectations and ethical advertising standards for professional firms.
reference from nigeria revenue service (nrs)
The nigeria revenue service (nrs) places emphasis on accurate record-keeping and supporting documentation for tax returns. This expectation typically includes maintaining invoices, contracts, proof of service delivery/supply, and evidence that tax positions taken in returns are supported by underlying transactions. For businesses, effective receivables tracking is how those records remain complete and consistent with actual settlement status.
---
how receivables monitoring works
Receivables generally represent amounts owed by customers for goods supplied or services rendered under credit terms. Monitoring is the structured process of:
1. recording invoices accurately with correct tax details (such as vat where applicable).
2. tracking due dates and payment status against the agreed terms.
3. escalating overdue accounts with documented follow-up.
4. reviewing collectability to assess risks of non-payment.
5. updating accounting records for receipts, adjustments, credit notes, or reversals.
6. linking financial updates to tax calculations and statutory filings.
A monitoring system can be manual, spreadsheet-based, or integrated into an accounting/erp system, but it must produce reliable audit trails.
---
step-by-step: how to implement receivables “monitoring” (invest in the right controls)
This section explains “how to invest” in a receivables monitoring setup—meaning investing in controls, processes, and systems rather than speculation.
step 1: define credit terms and authorization limits
Document:
- standard payment terms (e.g., net 30/45/60),
- approval levels for granting credit,
- required documentation before invoicing.
step 2: set up invoice and tax compliance fields
Ensure every invoice captures the information needed for tax support, such as:
- customer identification,
- invoice number and date,
- description of supply,
- amount and tax components (where applicable),
- reference to contracts or delivery notes.
step 3: create a receivables aging schedule
Prepare an aging report, commonly:
- 0–30 days,
- 31–60 days,
- 61–90 days,
- 91+ days.
This helps management identify overdue balances early.
step 4: establish a follow-up and escalation workflow
For example:
- 7 days before due date: reminder,
- due date + 1–7 days: follow-up call/email,
- overdue + 15 days: escalation to sales manager,
- overdue + 30 days: formal notice and request for settlement plan,
- overdue + 60/90 days: consider legal recovery steps where contract allows.
Keep evidence of all follow-ups.
step 5: reconcile receivables to accounting ledgers monthly
At month-end:
- reconcile customer sub-ledgers to the general ledger,
- verify unapplied cash,
- confirm credit notes and invoice cancellations.
step 6: review collectability for accounting and tax support
Conduct periodic assessments of whether certain balances are doubtful. The objective is consistent treatment in accounting and aligned documentation for tax computations.
step 7: link monitoring outputs to tax reporting processes
Ensure:
- cash receipts and adjustments are reflected in the accounting records,
- vat/wht positions remain supported by documents,
- any provisions or write-offs are backed by acceptable evidence and policy.
---
why receivables monitoring matters to taxpayers
For nigerian taxpaying businesses, receivables monitoring supports compliance in several areas:
1) defensible revenue reporting
If revenue is recognized based on delivery/supply, then invoices and delivery evidence must match. Monitoring helps confirm that recorded receivables correspond to actual taxable transactions.
2) vat accuracy on taxable supplies
Where vat applies, the business must align:
- invoices issued,
- taxable supplies,
- output vat declared,
- and any adjustments that arise from credit notes or returns.
If invoices are disputed or corrected, the receivables register and VAT records should be consistent.
### 3) Withholding tax (WHT) tracking (where applicable)
In many transactions, WHT may apply depending on the nature of supply and tax rules. Proper receivables records assist in:
- maintaining contract evidence,
- confirming invoicing basis,
- and tracking tax withheld for credit claims (where eligible under the tax regime in use).
### 4) Audit readiness
Tax assessments and reviews often depend on documentation. A monitoring system produces:
- invoice history,
- payment evidence,
- correspondence,
- and adjustments.
This reduces gaps that typically trigger queries.
---
## Tax Implications: Key Considerations
Receivables management affects taxes when there are events such as settlement, credit notes, disputes, write-offs, or late payments. Important points include:
### A) Credit sales and taxable event consistency
Tax positions generally depend on the nature of the transaction and the relevant tax law framework. A business must ensure that invoicing, delivery evidence, and tax treatment remain consistent.
### B) Bad debt and recoverability
If a receivable becomes irrecoverable, the accounting classification and tax treatment require careful documentation. Overstating deductions or changing positions without evidence can lead to disallowance and penalties.
Operationally, monitoring helps you detect issues early and maintain proper evidence if recovery later fails.
### C) Credit notes and adjustments
If a customer issues a credit note (or the supplier issues one due to returns, errors, or agreed adjustments), update:
- receivables,
- sales records,
- output VAT (where applicable),
- and the tax computation support.
### D) Timing issues
Late settlements can create differences between billing dates, receipt dates, and statutory filing deadlines. Monitoring reduces the risk of errors in reporting periods.
### E) Interest/penalties in contracts
If contracts include interest or penalties for late payment, ensure the accounting and tax treatment follow the agreed contract and the relevant tax framework. Documentation is essential.
-Advantages for Business Operations and Control
Monitoring receivables provides advantages that are measurable and practical:
1. Improved cash planning: earlier visibility of overdue balances supports working capital decisions.
2. Reduced revenue leakage: disputes and missed settlements are identified sooner.
3. Better credit risk management: you can review customer risk profiles and adjust credit terms.
4. Stronger internal controls: audit trails improve and reduce the likelihood of posting errors.
5. Faster resolution of tax record mismatches: VAT/WHT support is easier to reconcile.
6. More accurate financial reporting: aging, impairment views, and management accounts become reliable.
- Reasons Every Business Should Comply with Tax Regulation
Compliance is not only about avoiding enforcement actions. For businesses, it supports:
- consistent reporting: taxes are computed based on recorded transactions supported by documentation;
- predictable operations: fewer corrections close to filing dates;
- credibility in dealings: proper tax documentation supports credit applications, supplier relationships, and stakeholder reviews;
- reduced risk of disallowances: especially where deductions depend on proof.
Receivables monitoring strengthens the “documentation chain,” which is central to tax compliance.
---
Tips in Nigeria: Tax Credit Opportunities and Records to Keep
While tax rules differ by sector and transaction type, the common compliance approach is to ensure proper documentation for credits and lawful deductions. Practical tips include:
1. Keep WHT evidence where credits apply
- WHT certificates or remittance evidence (as applicable),
- invoices and contracts showing the nature of service/supply,
- and reconciliation of WHT credited to ledger entries.
2. Maintain VAT invoice discipline (where VAT is applicable)
- ensure VAT invoices are correct and consistent,
- track returns and credit notes,
- reconcile output VAT to the sales journal and receivables register.
3. Maintain delivery evidence
- signed delivery notes,
- acceptance letters,
- emails/acceptance confirmations.
4. Document disputes and settlement negotiations
If customers dispute invoices, keep written communications. This supports the accounting stance and any later tax adjustments.
5. Review write-off criteria
Only treat receivables as doubtful/irrecoverable when your internal policy and evidence supports it.
- Relevant Nigerian Tax Law Areas (Where Applicable)
Receivables monitoring touches multiple compliance areas commonly relevant to businesses in Nigeria, including:
- Income tax principles relating to revenue recognition, deductions, and supporting documentation.
- VAT rules applicable to taxable supplies, invoicing, output tax reporting, and adjustments through credit notes.
- Withholding tax compliance where applicable to the nature of transactions and statutory remittance/credit processes.
- Record-keeping and tax audit readiness under the general expectations of tax administration.
For a business-specific interpretation, the applicable tax law depends on:
- the nature of the business,
- the state of operation and registration,
- the transaction types (goods vs services),
- and the customer/supplier profile.
-
Professional Consulting Firm Support: How to Avoid Errors
When businesses monitor receivables without technical support, errors can occur, such as:
- invoices posted without correct tax details,
- credit notes applied late or to wrong periods,
- tax adjustments made without supporting documentation,
- aging reports disconnected from ledger and tax records.
A professional consulting firm can help by:
- reviewing credit policy and invoice workflows,
- aligning accounting treatment with tax documentation requirements,
- designing reconciliation routines between sales/receivables and tax computations,
- and documenting decisions for audit defensibility.
Where needed, US & CO. (Chartered Accountant) can support structured controls that reduce avoidable risk while keeping management reports consistent with tax reporting processes.
---
Ethical Next Step (If You Need Further Assistance)
Where you need further assistant: Contact Professional Tax Consulting Firm in Lagos **Nigeria** on:
📞 WhatsApp: 08056219998
📧 Email: info@usc.com.ng
🌐 Website: https://www.usc.com.ng